Categories
Boise Mortgage RatesPublished October 29, 2026
Boise Home Loan Guide 2027: Credit Scores, Down Payments & Loan Options Explained

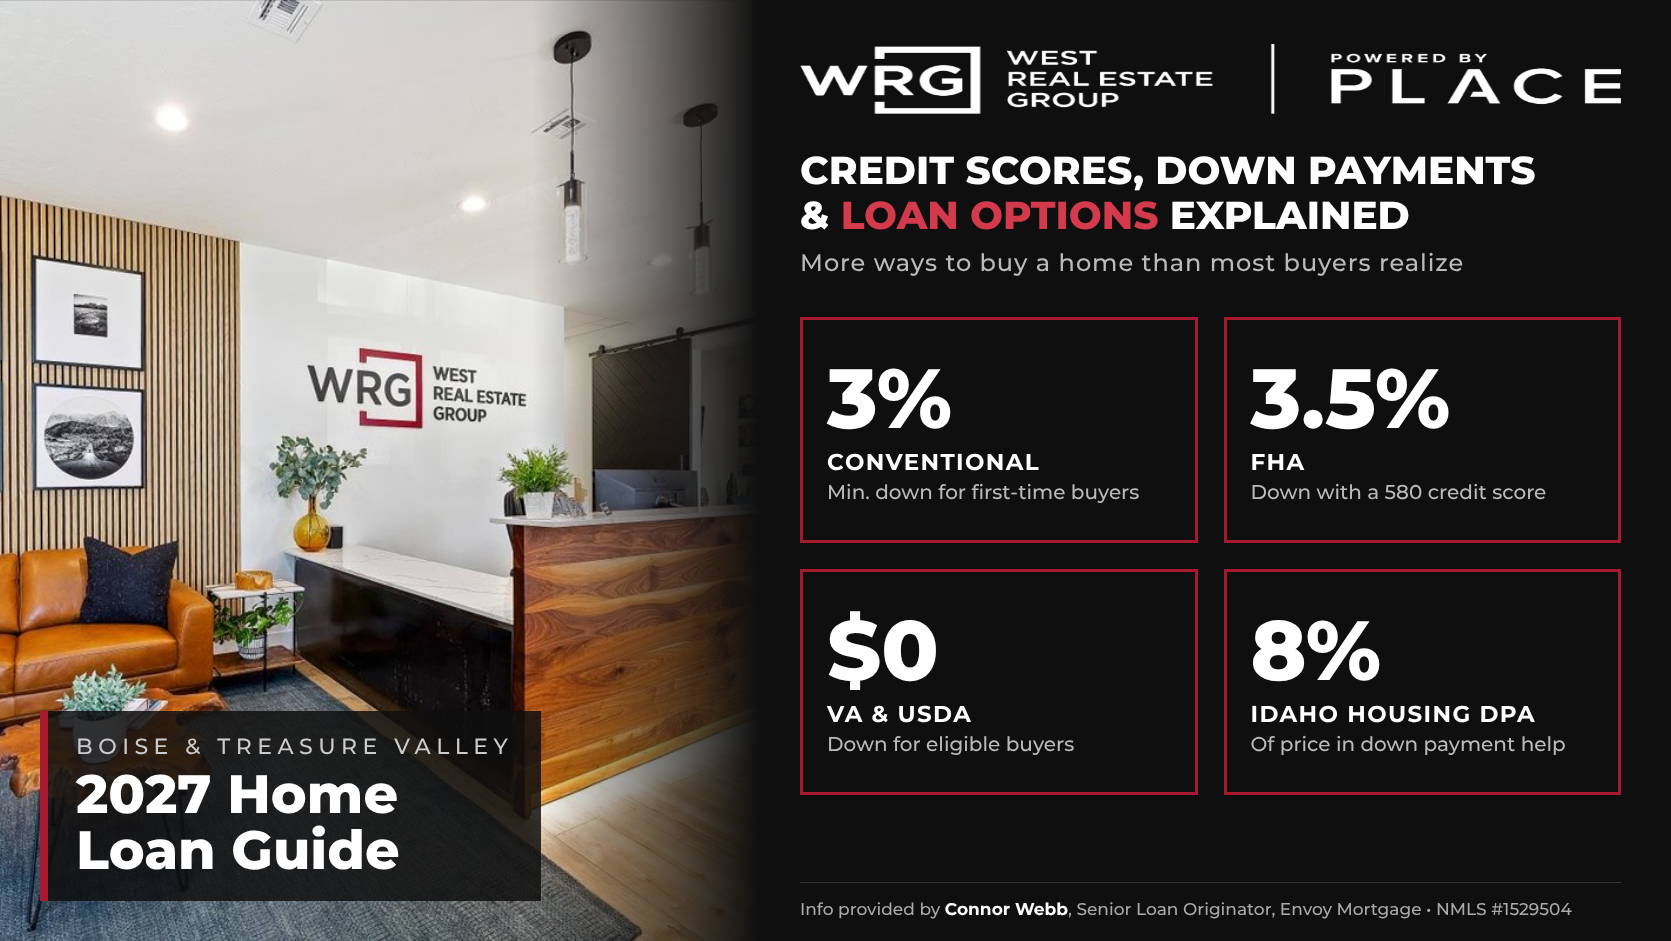
Boise Home Loan Guide 2027: Credit Scores, Down Payments & Loan Options Explained
More ways to buy a home in the Treasure Valley than most buyers realize
One of the most common things we hear from buyers is, "I don't think I can qualify."
More often than not, that isn't true.
From 3% down conventional loans to $0 down VA and USDA loans, plus Idaho down payment assistance, there are more paths to homeownership than most people know about.
To break it all down, West Real Estate Group teamed up with our lending partner Connor Webb, Senior Loan Originator at Envoy Mortgage (NMLS #1529504).
All lending information in this post comes from Connor's 2027 Guide to Mortgage Lending for Boise and the Treasure Valley.
📊 2027 HOME LOAN SNAPSHOT
| Loan Program | Typical Min. Credit Score | Min. Down Payment | Good to Know |
|---|---|---|---|
| Conventional | About 620 | 3% first-time / 5% repeat | Best pricing at 700+; PMI can be removed |
| FHA | 580 (500–579 with 10% down) | 3.5% | Credit-flexible; gift funds OK |
| VA | No VA minimum (lenders about 580–620) | $0 | No monthly mortgage insurance |
| USDA | 640 for streamlined approval | $0 | Address and income must qualify |
| Jumbo | 680–720+ | 10–20% | Loans over $845,000* |
| DSCR / Bank Statement / ITIN | About 620–680 | 10–25% | Self-employed and investor buyers |
Source: Connor Webb, Envoy Mortgage. Typical guidelines as of October 2026; lender requirements vary. *Early 2027 figure.
🔥 THE BIGGEST MYTH: YOU NEED 20% DOWN
You don't.
First-time buyers can put as little as 3% down on a conventional loan.
FHA loans require just 3.5% down.
Eligible veterans and buyers in USDA areas can put $0 down.
According to Connor, the "20% myth" stops more would-be buyers than interest rates do.
HOW LENDERS DECIDE IF YOU QUALIFY
Every lender is answering the same four questions, known as the "4 C's":
- Credit: your score and history
- Capacity: your debt-to-income ratio (DTI)
- Capital: your down payment and savings
- Collateral: the home's appraised value
The big one is DTI: all monthly debt payments, including the new house payment, divided by your gross monthly income.
For example, a buyer earning $8,000 a month with $800 in debts and a $2,800 house payment is at 45% DTI.
That's approvable on most loan programs.
WHAT CREDIT SCORE DO YOU NEED TO BUY A HOUSE IN BOISE?
Probably less than you think.
FHA loans allow a 580 score with 3.5% down. Scores of 500–579 may be possible with 10% down.
Conventional loans no longer have a hard 620 minimum at Fannie Mae or Freddie Mac, though most lenders still look for about 620.
Connor's rule of thumb:
- 700+ credit score: conventional usually offers the best pricing
- Below 700 with less than 20% down: compare FHA too, because it often wins on monthly payment
CONVENTIONAL LOANS: THE MOST POPULAR CHOICE
About 7 in 10 purchase loans are conventional.
They offer the most competitive pricing for buyers with solid credit, and they're the only option here for second homes and investment properties.
- 3% down for first-time buyers, 5% for repeat buyers
- DTI up to 50% with automated approval
- PMI can be cancelled at about 20% equity
- The entire down payment can be a gift on a primary residence
FHA LOANS: FLEXIBLE CREDIT, LOW DOWN PAYMENT
FHA was built for buyers whose credit isn't perfect.
- 3.5% down with a 580 credit score
- DTI up to 57% with automated approval, the highest of any standard program
- Possible 2–3 years after a bankruptcy or foreclosure
- Sellers can contribute up to 6% toward closing costs
- Assumable, so a future buyer could take over your rate
Mortgage insurance is 1.75% upfront (usually financed) plus about 0.55% per year.
The Boise-area FHA limit (Ada, Canyon, Boise, Gem and Owyhee Counties) is $586,500 for 2026, with HUD's 2027 number expected in December.
US VA LOANS: $0 DOWN FOR THOSE WHO SERVED
If you or your spouse served, start here.
VA loans offer $0 down and no monthly mortgage insurance, which Connor calls the strongest math in lending.
- No VA minimum credit score (most lenders look for about 580–620)
- No hard DTI cap; approvals up to about 60% with strong residual income
- No loan limit with full entitlement anywhere in Idaho
- Sellers can pay all closing costs plus up to 4% in concessions
A one-time funding fee (about 2.15% for first use) replaces monthly mortgage insurance, and it's waived for veterans with service-connected disability ratings.
🌾 USDA LOANS: $0 DOWN JUST OUTSIDE THE CITY
Connor calls USDA the best-kept secret in lending.
Much of Idaho outside the Boise-Nampa metro core qualifies, including many commutable areas.
- $0 down payment
- Household income at or below 115% of area median
- 640 credit score for streamlined approval
- The lowest government mortgage insurance: 1% upfront plus 0.35% per year
Browsing homes in Star, Middleton, Kuna or Emmett? Send us the address and we'll have it checked for USDA eligibility.
💡 IDAHO DOWN PAYMENT ASSISTANCE
"We just don't have enough saved" doesn't have to be the end of the conversation.
Idaho Housing (IHFA) Down Payment Assistance offers up to 8% of the sales price toward down payment and closing costs.
It's a repayable second mortgage for households earning under $170,000, and a homebuyer education course is required. Repeat buyers can use it too.
Click n' Close SmartBuy™ offers up to 5% toward down payment, closing costs or a rate buydown, paired with an FHA or USDA loan. There are no income limits and no first-time buyer requirement.
Pairing a $0 down USDA loan with assistance for closing costs can mean a near-zero out-of-pocket purchase.
There's also the Idaho Heroes Loan for first responders, teachers, nurses and veterans.
Down payment assistance is not just for first-time buyers. Funding and terms change, so always verify current availability with a lender.
2027 LOAN LIMITS FOR THE TREASURE VALLEY
| Loan Limit (1-unit home) | Amount |
|---|---|
| Conforming (conventional) | $845,000* (up from $832,750 in 2026) |
| FHA, Boise area | $586,500 for 2026; 2027 number expected in December |
| VA with full entitlement | No limit |
| Jumbo | Loans above $845,000* |
*Early 2027 figure adopted by major lenders ahead of FHFA's official announcement, expected late November 2026. Final numbers may differ slightly.
With the higher conforming limit, more Treasure Valley buyers can use a low-down-payment conventional loan.
Some buyers who were just over the old limit may now get conforming pricing instead of jumbo.
SELF-EMPLOYED, INVESTING OR MOVING UP?
If your finances don't fit the standard W-2 box, there's likely still a loan for you:
- Bank statement loans: self-employed buyers qualify on deposits instead of tax returns
- DSCR loans: investors qualify on the property's rent
- ITIN loans: for buyers who file taxes with an ITIN
- Bridge loans / HELOCs: buy your next home before selling your current one
- Temporary buydowns (2-1, 3-2-1): a seller-paid credit that lowers your rate for the first years
Thinking about moving up? Start with a free home value estimate to see how much equity you have to work with.
✅ PROTECT YOUR LOAN ONCE YOU'RE UNDER CONTRACT
A typical purchase closes in 21–30 days.
Connor's top tips to keep your closing on track:
- Do get fully pre-approved before you start touring homes
- Do send requested documents the same day
- Do tell your lender right away about job changes or gift funds
- Don't finance a car or furniture, or open new credit
- Don't move large sums between accounts without a paper trail
- Don't co-sign for anyone or miss a payment
⭐ WRG INSIGHT
"The buyer who thinks they can't afford to buy usually can. They just haven't met the right loan program yet. Between FHA, VA, USDA and Idaho's down payment assistance options, there are more paths to homeownership in the Treasure Valley than most people realize."
FREQUENTLY ASKED QUESTIONS
What is the minimum credit score to buy a house in Idaho?
FHA loans allow a 580 score with 3.5% down, and 500–579 may be possible with 10% down. Conventional loans typically start around 620. VA and USDA have no official minimum, though lenders set their own.
How much do I need for a down payment in Boise?
As little as $0 with VA or USDA, 3% for first-time buyers on a conventional loan, or 3.5% with FHA. Idaho Housing's program can provide up to 8% of the sales price in assistance.
What is the 2027 conforming loan limit?
Major lenders have adopted an early 2027 limit of $845,000 for most counties, up from $832,750 in 2026. FHFA's official announcement is expected in late November 2026.
Can I buy a home in Boise with no money down?
Yes, if you're an eligible veteran (VA) or buying in a USDA-eligible area with qualifying income. Pairing either with down payment assistance can help cover closing costs too.
FINAL THOUGHTS
Whether you're a first-time buyer, a veteran, self-employed or ready to move up, there's likely a loan program that fits.
The key is talking to the right people before you rule yourself out.
A big thank you to Connor Webb of Envoy Mortgage for sharing his expertise for this guide.
Learn more on our Financing and Buying pages.
🏡 READY TO SEE WHAT YOU QUALIFY FOR?
Start with a conversation, not a credit pull.
Call or text West Real Estate Group and we'll walk you through your options and connect you with Connor for a same-day loan scenario review.
Whether you're searching in Boise, Meridian, Eagle, Nampa, Caldwell or anywhere in the Treasure Valley, our team is here to help.
West Real Estate Group
Treasure Valley Real Estate
208-501-8200
Lending information provided by Connor Webb, Senior Loan Originator, Envoy Mortgage, NMLS #1529504. Envoy Mortgage, Ltd. NMLS #6666. Equal Housing Opportunity. Program guidelines, credit score minimums, DTI allowances and mortgage insurance figures are typical industry standards as of October 2026 and are subject to change without notice; lender overlays may apply. 2027 loan limits shown are early figures; final FHFA and HUD limits may differ. This is not a commitment to lend. All borrowers are subject to credit approval.
John West
Operator / Designated Broker | West Real Estate Group | PLACE
or another way